A real example: what a $80,000 salary buys
Say your household earns $80,000 a year — about $6,667 a month before tax. The 28% rule says your total housing payment should stay under 28% of gross income:
$6,667 × 28% = about $1,867 a month for principal, interest, taxes and insurance combined.
At a 7% mortgage rate with 20% down, and property tax plus insurance at 1.5% of the home's value a year (the calculator's default), that payment supports a home priced around $284,000. Lower taxes and insurance raise that figure; higher ones cut it. Carry other debts like a car or student loans and lenders shrink that number through the 36% total-debt rule. Enter your income and debts above for your own price range.
How much house can you afford?
This calculator works backward from your income. It finds the largest monthly housing payment that fits the 28/36 rule, subtracts estimated taxes and insurance, and solves for the home price your mortgage could cover with your down payment.
The two limits lenders check, and when debts start to matter
The 28/36 rule is really two separate caps, and whichever is lower sets your budget. The first: housing costs under 28% of gross income. The second: housing plus all other debt payments under 36%. The gap between them is 8% of your gross monthly income, and that gap is a threshold. Debts below it don't change your budget at all; every dollar above it comes straight off your housing payment.
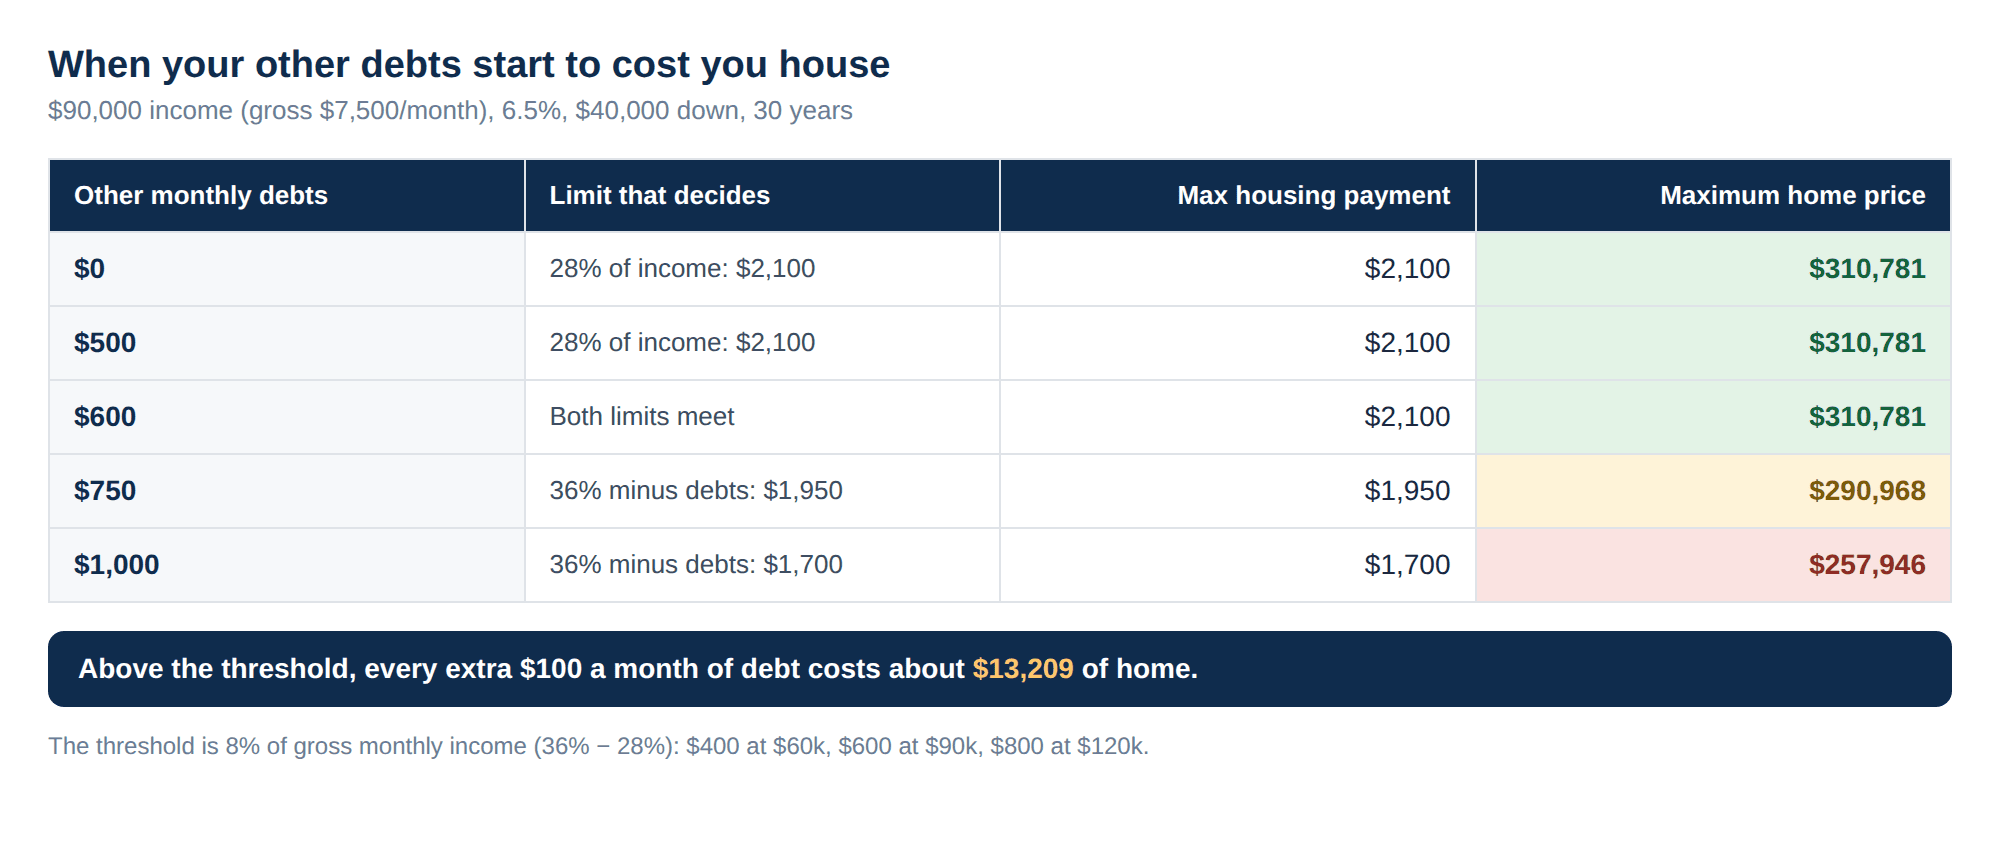
On a $90,000 income the threshold is $600 a month. Below that, a car payment or student loan doesn't touch what you can borrow. Above it, each extra $100 a month costs about $13,209 of purchase price at 6.5%. Paying off a small loan before you apply can be worth far more than it looks. Check your own ratio with the debt-to-income calculator, and see how a car lease fits into it in car leases and your debt-to-income ratio.
How much your mortgage rate moves the number
Your income sets the payment you can afford; the rate decides how much house that payment buys. Same income, same $2,100 a month:
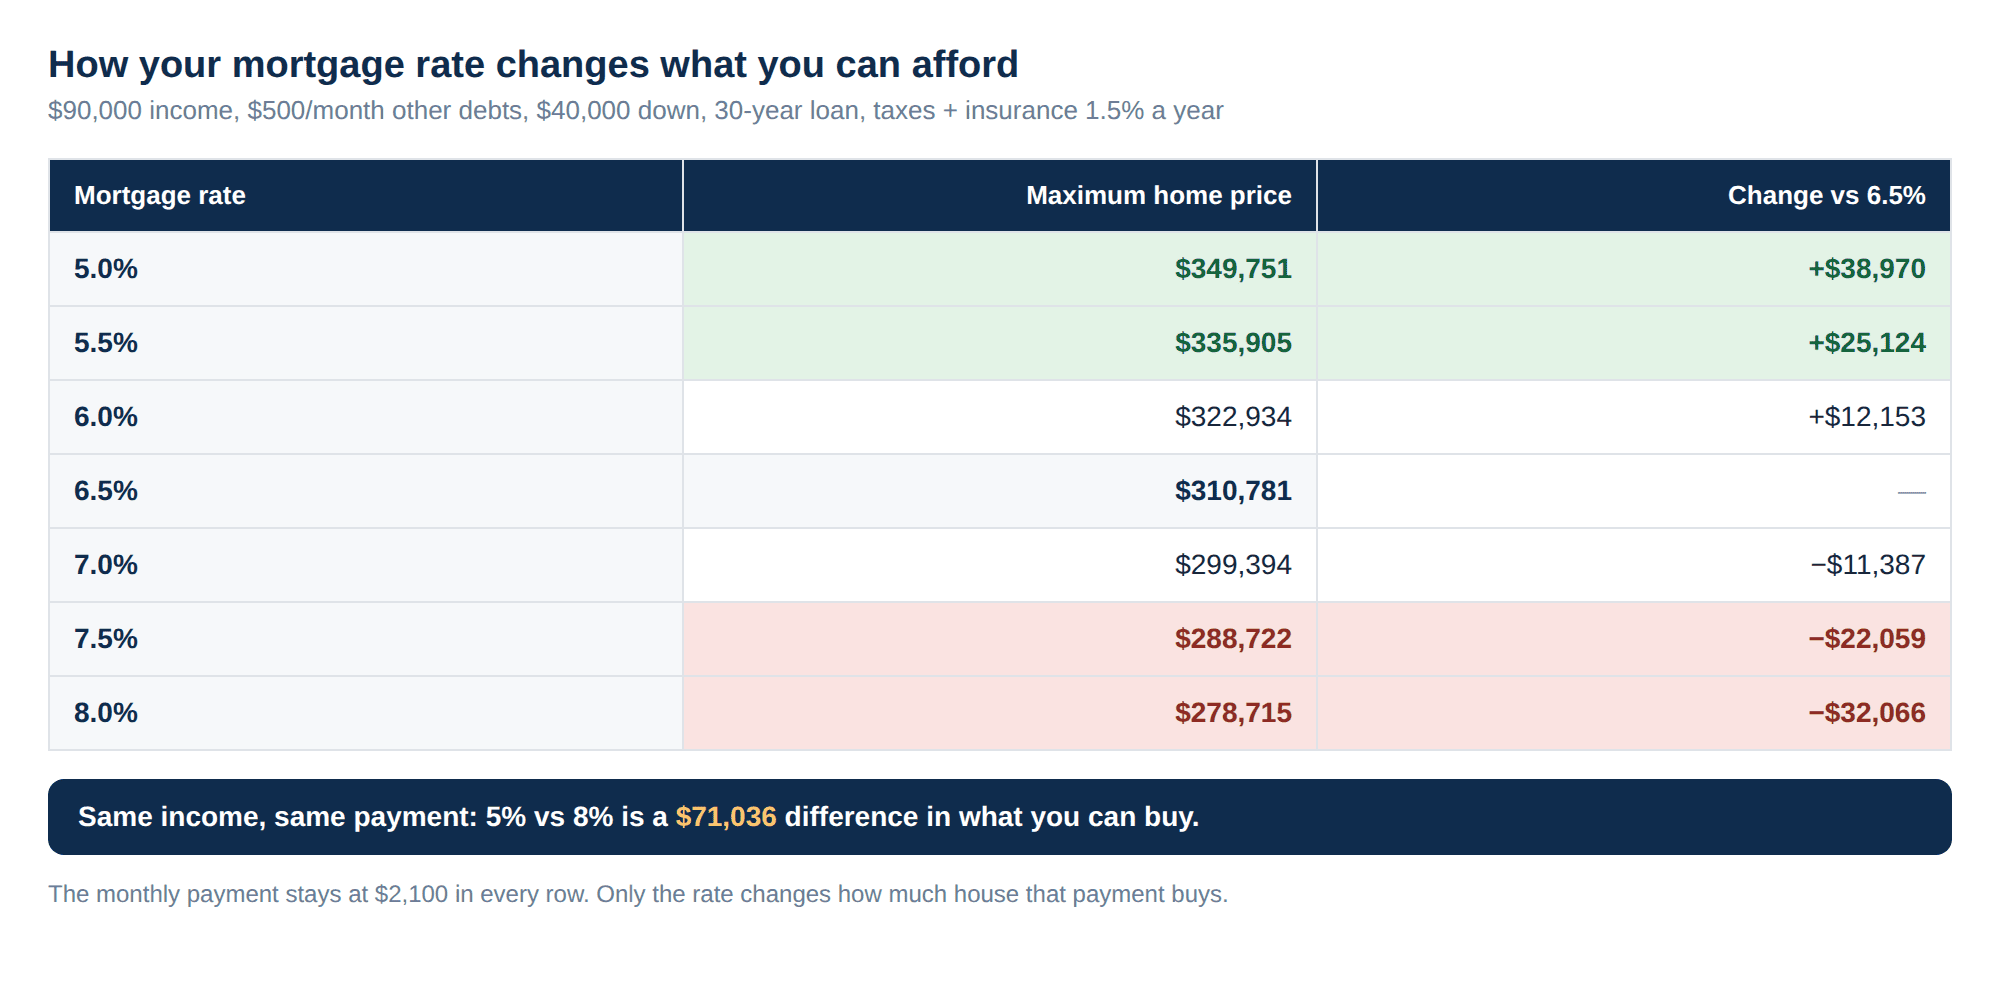
Each half point is worth roughly $10,000 to $14,000 of home price at this income. That is why shopping for a rate matters as much as shopping for a house. The term matters too: switch the same inputs from a 30-year to a 15-year loan and the maximum drops from $310,781 to $245,801, because the payment has to repay the loan twice as fast.
A smart-money caveat
This shows your maximum — not your ideal. Buying below the max leaves room to invest, build an emergency fund, and handle surprises. Many people deliberately spend less than they qualify for. For more, read how much house can I afford?
When this calculator's answer can mislead you
- A lender may approve more. 28/36 is a common guideline, not a hard rule, and many loan programs allow higher ratios. Being approved for more isn't a reason to spend more.
- Mortgage insurance isn't included. With less than 20% down, most conventional loans add private mortgage insurance (PMI) to the payment. The calculator's own defaults put only 12.9% down, so the real payment there would be higher than shown.
- Taxes and insurance vary widely. 1.5% of the home's value a year is a rough starting point. Look up actual property tax rates and get an insurance quote for the area you're buying in, then enter your own figure.
- HOA fees, maintenance and utilities aren't in the payment at all, but they come out of the same budget.
- Your down payment isn't all your cash. Closing costs come on top. See how much closing costs really are before you commit every dollar to the deposit.
- It uses gross income. 28% of gross pay is a much bigger share of what lands in your account. Run your take-home through the paycheck calculator and make sure the payment still feels comfortable.
Next steps
Mortgage rates
A lower rate increases how much home you can afford — shop around.
Compare lenders →Mortgage Calculator
See the full monthly payment and lifetime cost of a specific home.
Open calculator →Frequently asked questions
Does this include the down payment in affordability?
Yes — a bigger down payment means a smaller loan and a higher home price you can afford for the same monthly payment.
What's the 28/36 rule?
Keep housing costs under 28% of gross income and total debt payments under 36%. It's a widely used guideline; many loan programs allow higher ratios, so a lender may approve more than this calculator shows.
How much house can I afford on $90,000 a year?
Using the 28/36 rule with $500 a month of other debts, a $40,000 down payment, a 6.5% 30-year mortgage and taxes plus insurance at 1.5% a year, about $310,781. Your rate, debts, down payment and local taxes all change that, so enter your own figures above.
Does a car payment affect how much house I can afford?
Only once your total monthly debts pass 8% of your gross monthly income, which is $600 a month on a $90,000 income. Above that, each extra $100 a month of debt cuts the home price you can afford by about $13,209 at 6.5%.
How much does a higher mortgage rate reduce what I can afford?
At $90,000 of income, moving from 6.5% to 7.5% cuts the maximum home price from $310,781 to $288,722, about $22,000 less for the same monthly payment.
Does this calculator include PMI?
No. With less than 20% down, most conventional loans add private mortgage insurance to the monthly payment, so your real payment would be higher than shown. HOA fees are not included either.
Should I buy the most house I can afford?
Usually not. The result is a ceiling, not a target. Buying below it leaves room for an emergency fund, retirement saving and the costs of owning a home that are not in the mortgage payment.
Related tools
Check your debt-to-income ratio or compare with rent vs buy.